Morocco’s SMEs Gain New Financing Capacity Through IFC–Tamwilcom Partnership – GTsetu
🔴 BREAKINGIFC–Tamwilcom partnership creates new risk-sharing facility to unlock financing for Moroccan SMEs◆Focus on agricultural businesses and supply chain companies — key sectors for Morocco’s economy◆Expected to unlock hundreds of millions in SME lending capacity across Morocco◆Find verified agri-finance and SME partners on GTsetu — 100+ countries, zero commission◆🔴 BREAKINGIFC–Tamwilcom partnership creates new risk-sharing facility to unlock financing for Moroccan SMEs◆Focus on agricultural businesses and supply chain companies — key sectors for Morocco’s economy◆Expected to unlock hundreds of millions in SME lending capacity across Morocco◆Find verified agri-finance and SME partners on GTsetu — 100+ countries, zero commission◆
Morocco’s SMEs Gain New Financing Capacity Through IFC–Tamwilcom Partnership
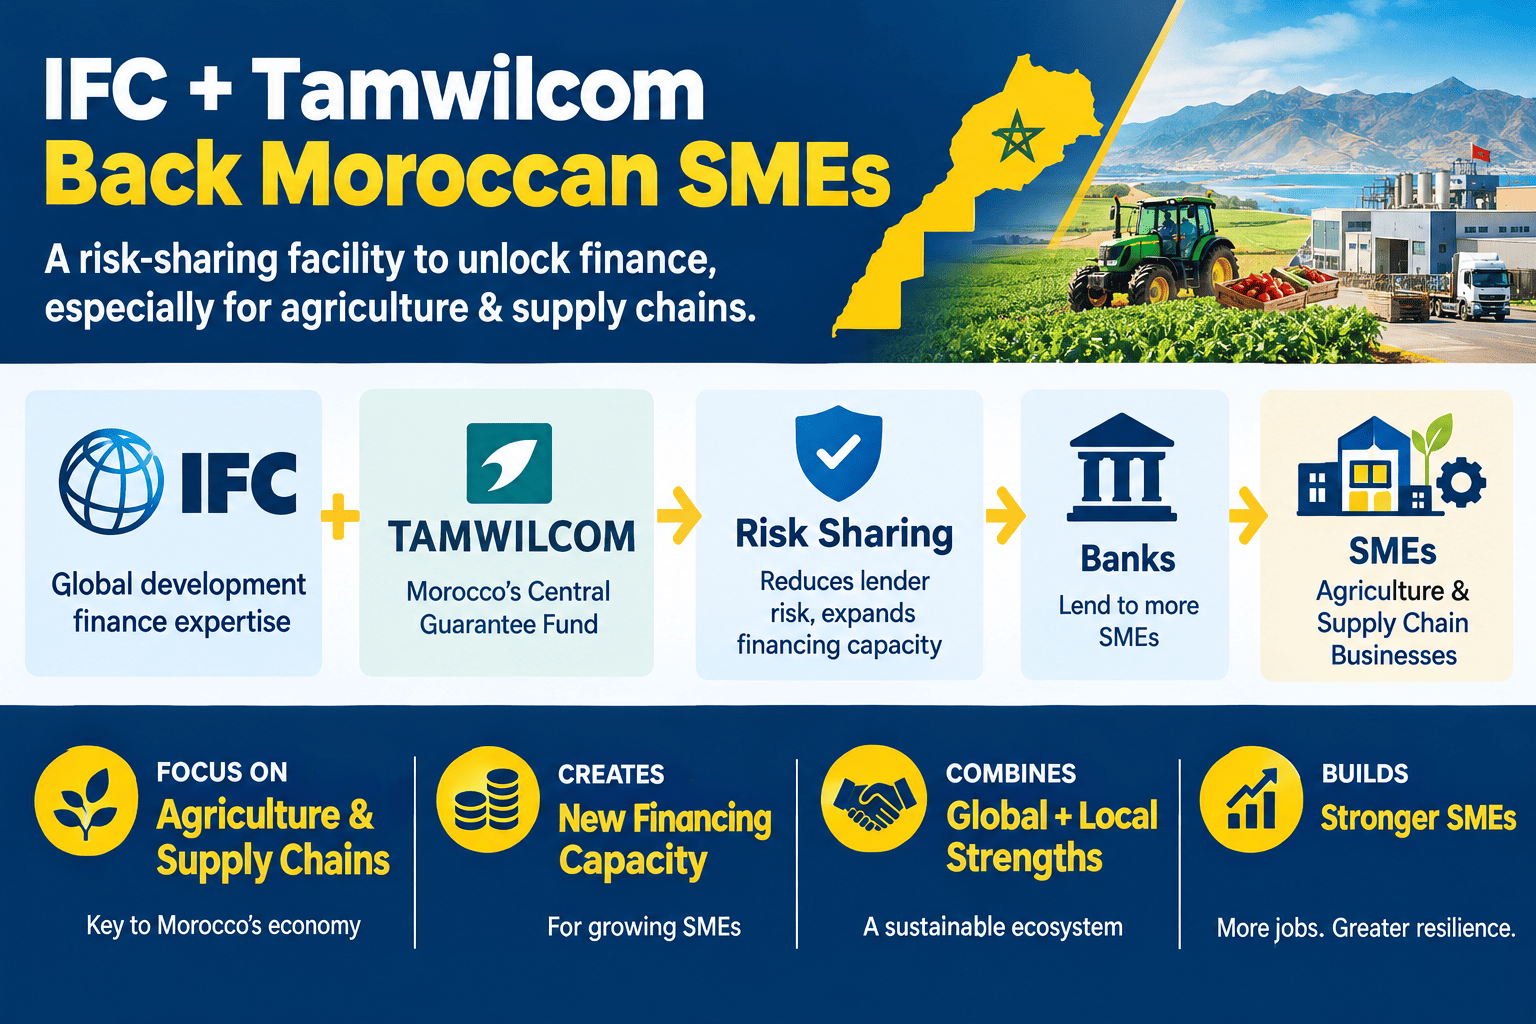
The International Finance Corporation (IFC) and Tamwilcom, Morocco’s Central Guarantee Fund, have created a risk-sharing facility to support Moroccan SMEs, including agricultural businesses and companies operating in supply chains. The facility is designed to unlock new financing capacity by reducing bank risk exposure.
🎯 Direct Answer
The International Finance Corporation (IFC) and Tamwilcom, Morocco’s Central Guarantee Fund, have created a risk-sharing facility to support Moroccan SMEs, including agricultural businesses and companies operating in supply chains. The facility is a strategic alliance designed to unlock new financing capacity by reducing the risk exposure of banks lending to SMEs. Under the arrangement, IFC and Tamwilcom share the credit risk of SME loans, enabling banks to lend to segments they might otherwise consider too risky. The initiative is particularly focused on agriculture and supply chain companies, which are critical to Morocco’s economy but often face financing constraints. This is a manufacturer and services partnership model, combining IFC’s global development finance expertise with Tamwilcom’s local guarantee infrastructure to create a sustainable SME financing ecosystem.
📅 April 17, 2026⏱ 16 min read✍️ GTsetu Editorial Team📰 News + Analysis
IFC and Tamwilcom share credit risk to unlock bank lending
Focus Sectors
2
Agriculture · Supply Chain Companies
MENA Region
Morocco
Middle East & North Africa (Non-GCC) · MENA cluster
Section 1 — The News
1
The Full Story: IFC × Tamwilcom Risk-Sharing Facility
🏦
Strategic Alliance Announced — April 2026
IFC and Tamwilcom Launch Risk-Sharing Facility to Unlock Financing for Moroccan SMEs in Agriculture and Supply Chains
In April 2026, the International Finance Corporation (IFC) and Tamwilcom, Morocco’s Central Guarantee Fund, announced a new risk-sharing facility designed to support Moroccan SMEs, including agricultural businesses and companies operating in supply chains.
The facility is a strategic alliance that combines IFC’s global development finance expertise with Tamwilcom’s local guarantee infrastructure. Under the arrangement, IFC and Tamwilcom share the credit risk of SME loans, enabling banks to lend to segments they might otherwise consider too risky.
The initiative is particularly focused on agriculture and supply chain companies, which are critical to Morocco’s economy but often face financing constraints. The facility is expected to unlock hundreds of millions in SME lending capacity, supporting job creation, economic growth, and supply chain resilience across Morocco.
Risk-Sharing
IFC and Tamwilcom share credit risk to unlock bank lending to SMEs
2
Focus sectors: agriculture and supply chain companies
Strategic
Strategic alliance: IFC global expertise + Tamwilcom local infrastructure
MENA
Morocco, Middle East & North Africa (Non-GCC) region
“This risk-sharing facility is a strategic alliance that combines IFC’s global development finance expertise with Tamwilcom’s local guarantee infrastructure. By sharing credit risk, we enable banks to lend to Moroccan SMEs in agriculture and supply chains, unlocking new financing capacity and supporting economic growth.”
— IFC and Tamwilcom Joint Statement, April 2026
💡 GTsetu Perspective
The IFC–Tamwilcom risk-sharing facility represents a structural shift in SME finance in Morocco. For agricultural businesses and supply chain companies, this is a new pathway to financing that was previously inaccessible. For banks, it’s a way to lend to SMEs with reduced risk. The question is no longer whether to engage with SME finance, but with whom and how fast. GTsetu connects you to verified agri-finance and SME partners across MENA and 100+ countries, so you can access these opportunities before your competitors do.
Section 2 — How It Works
2
How the Risk-Sharing Facility Works
The IFC–Tamwilcom risk-sharing facility is built on a clear, measurable objective: unlock new financing capacity for Moroccan SMEs, particularly in agriculture and supply chains. The execution model is based on risk-sharing, which reduces the risk exposure of banks lending to SMEs.
🇲🇦 Risk-Sharing Facility — How It Unlocks SME Financing
Step 1
Risk Assessment
IFC & Tamwilcom Identification
Step 2
Risk Sharing Agreement
IFC & Tamwilcom ● Live
Step 3
Banks Lend to SMEs
Banks Target
⚙️ Why Risk-Sharing Is the Critical First Step
The IFC–Tamwilcom risk-sharing facility correctly identifies risk as the foundational barrier to SME financing in Morocco. Agricultural businesses and supply chain companies are often considered too risky by banks, even when they have viable business models. By sharing credit risk, IFC and Tamwilcom reduce the bank’s exposure, making lending to these segments viable. The sequence — risk-sharing first, lending second — is the right order for any SME finance facilitation initiative.
Section 3 — The Anatomy
3
What Each Partner Brings to the Table
Like every successful SME finance collaboration, the IFC–Tamwilcom partnership works because each party contributes assets that the other cannot efficiently replicate. This complementarity principle is the foundation of any finance partnership worth entering.
IFC’s capital meets Tamwilcom’s local infrastructure
Market Access
Provides global best practices, risk assessment
Provides Moroccan bank network, SME reach
Both parties unlock new lending capacity for each other
Risk Mitigation
Provides risk-sharing, global risk expertise
Provides local guarantee, market knowledge
Risk is shared between global and local expertise
SME Development
Provides capacity building, advisory services
Provides local SME outreach, guarantee programs
SMEs get both global expertise and local support
Impact
Expanded SME financing in Morocco
New lending capacity for Moroccan banks
Both parties contribute to Morocco’s economic growth
Section 4 — Why This Works
4
Why This Collaboration Model Works for SME Finance
🎯 The Core Logic
The IFC–Tamwilcom risk-sharing facility succeeds because it addresses a structural market failure: Moroccan SMEs in agriculture and supply chains have viable business models but lack access to financing due to bank risk aversion. IFC has global risk capital and development finance expertise but lacks local market infrastructure. By combining IFC’s risk capital and global expertise with Tamwilcom’s local guarantee infrastructure and bank network, the partnership creates a structured, scalable pathway for SME financing that neither party could have built alone.
Why SME Finance Collaboration Is Accelerating in 2026
Risk-Sharing
Risk-sharing is the critical mechanism — banks lend when risk is shared
Agriculture
Agriculture is a key focus — critical to Morocco’s economy but financing-constrained
Supply Chain
Supply chain companies are a priority — strengthening Morocco’s industrial ecosystem
IFC
IFC brings global development finance expertise and risk capital
Tamwilcom
Tamwilcom provides local guarantee infrastructure and bank relationships
Morocco
Morocco is the anchor — MENA (Non-GCC) region, strategic gateway to Africa
Section 5 — Morocco Opportunity
5
Morocco’s SME Financing Opportunity — Why Now Is the Time to Partner
🇲🇦 Morocco SME Finance 2026–2030
Why Every SME Finance Provider Should Be Looking at Morocco
Morocco has a large and growing SME sector, with agriculture and supply chains playing a critical role in the economy. However, access to financing remains a persistent challenge for these segments. The IFC–Tamwilcom risk-sharing facility is designed to address this gap by reducing bank risk exposure and unlocking new lending capacity. The partnership is a model for SME finance facilitation across MENA and beyond.
Risk-Sharing
The critical mechanism — IFC and Tamwilcom share credit risk
2
Focus sectors: agriculture and supply chain companies
IFC
IFC brings global development finance expertise and risk capital
Tamwilcom
Tamwilcom provides local guarantee infrastructure and bank relationships
MENA
Morocco is the anchor — MENA (Non-GCC) region, gateway to Africa
Strategic
Strategic alliance — manufacturer and services partnership model
6
4 Types of SME Finance Collaboration — Which Fits Your Situation?
The IFC–Tamwilcom risk-sharing facility is a strategic alliance model. But SME finance collaborations come in many forms. The right structure depends on your role in the ecosystem, your capabilities, and your objectives.
01
Risk-Sharing Facility
A guarantor shares the credit risk of loans made by banks to SMEs. The IFC–Tamwilcom model. Best when banks are risk-averse and SMEs need financing. Unlocks lending capacity by reducing bank risk exposure.
🏦 IFC × Tamwilcom
02
Guarantee Program
A guarantee fund provides partial guarantees for SME loans, reducing bank risk. Tamwilcom’s core function. Best when banks need additional comfort to lend to specific SME segments, such as agriculture or supply chains.
🛡️ Guarantee program
03
Supply Chain Finance
Financing provided to suppliers based on the creditworthiness of the buyer. Best when large corporates want to support their SME suppliers. Reduces financing costs and improves supply chain resilience.
🔗 Supply chain finance
04
Co-Lending Partnership
Bank and development finance institution jointly fund SME loans. Shared risk, shared reward. Best for expanding credit access to underserved segments where one partner has origination capability and the other has capital.
💰 Co-lending model
Section 7 — How to Build
7
How to Build a Risk-Sharing Partnership: A 5-Step Playbook
The IFC–Tamwilcom partnership demonstrates how development finance institutions and local guarantee funds can collaborate to unlock SME financing. Here is the distilled playbook for building your own risk-sharing partnership.
1
Define the Financing Gap and Target SME Segment
IFC and Tamwilcom identified the specific gap: Moroccan SMEs in agriculture and supply chains have viable business models but lack access to financing due to bank risk aversion. Define your financing gap with precision: Which SME segments are underserved? What is the average loan size? What is the current financing gap? Vague gaps produce vague partnerships.
2
Find Verified Finance Partners — Not Just Any Institution
IFC and Tamwilcom are established, credible institutions. For businesses seeking finance partnerships, the crucial word is “verified.” GTsetu provides verified company profiles across MENA and 100+ countries. Every company is verified on 6 government-sourced points: Name, Address, Registration Number, Company Status, Company Type, and Date of Certificate of Incorporation. Additional information like regulatory approvals and track record is self-reported and should be validated independently.
3
Structure the Risk-Sharing Agreement
IFC and Tamwilcom structured a risk-sharing facility with clear terms: how risk is shared, which SME segments are eligible, and what the guarantee coverage is. Every risk-sharing partnership needs formal documentation: risk-sharing agreement, guarantee facility agreement, or co-lending agreement. GTsetu’s collaboration workspace supports this with secure document exchange and encrypted communications.
4
Implement Bank Onboarding and SME Outreach
The facility requires banks to participate and SMEs to be aware of the financing opportunity. Define the operational workflow: How will banks be onboarded? What are the eligibility criteria for SMEs? How will SMEs be reached? What training and support will be provided? The sequence is bank onboarding first, SME lending second.
5
Launch, Monitor, and Scale — Track SME Financing Impact
The facility targets hundreds of millions in SME lending capacity. Define success metrics: volume of loans guaranteed, number of SMEs reached, default rate, job creation. GTsetu helps you track partnership performance and identify opportunities for scaling into new sectors or regions.
Section 8 — Dos and Don’ts
8
Dos and Don’ts of SME Finance Collaboration
✅ Do These
✅ Partner with established, credible finance institutions like IFC and Tamwilcom
✅ Define target SME segments and financing gaps before structuring the facility
✅ Include risk-sharing as a core component, not an afterthought
✅ Structure the partnership with formal agreements and clear roles
✅ Focus on specific sectors where SMEs have viable business models
✅ Include bank onboarding and SME outreach as core components
✅ Verify your partner’s registration and credentials before engaging
✅ Use verified platforms like GTsetu for finance partner discovery
✅ Measure success by SME financing outcomes, not just partnership announcements
❌ Avoid These
❌ Announce a partnership without a clear implementation plan and timeline
❌ Ignore risk-sharing — banks won’t lend to risky segments without it
❌ Partner with an institution without verifying its credentials or track record
❌ Focus only on guarantees without SME outreach and capacity building
❌ Ignore bank onboarding — banks are the delivery channel for SME financing
❌ Sign an agreement without clear risk-sharing terms or implementation mechanisms
❌ Assume that a risk-sharing facility automatically creates lending — it needs execution
❌ Neglect monitoring and evaluation — risk-sharing requires careful tracking
❌ Fail to measure outcomes — partnerships without metrics cannot be scaled
Section 9 — Misconceptions
9
Common Misconceptions That Kill Risk-Sharing Partnerships
❌ Myth
“A risk-sharing agreement is enough — banks will automatically lend to SMEs.”
✅ Reality
The risk-sharing agreement is the framework, not the lending flow. Bank onboarding, SME outreach, and capacity building are the execution mechanisms that create actual lending. A partnership without an implementation plan is just a press release. The target of hundreds of millions in lending capacity and the focus on agriculture and supply chains demonstrate that execution is the priority.
❌ Myth
“Guarantees are the most important thing — SMEs just need banks to lend.”
✅ Reality
Guarantees are important, but SME readiness and bank capability are the critical first steps. SMEs need to understand the financing options, prepare bankable proposals, and manage their credit. Banks need to be onboarded to the facility and trained on its use. The IFC–Tamwilcom partnership correctly combines risk-sharing with bank onboarding and SME outreach. Without SME readiness, guarantees don’t translate into lending.
❌ Myth
“Any finance institution can partner with any other — it’s just a funding arrangement.”
✅ Reality
IFC and Tamwilcom are complementary institutions with proven track records — IFC has global risk capital and development finance expertise, Tamwilcom has local guarantee infrastructure and bank relationships. The partnership works because the capabilities are complementary and the institutions are credible. Partnering with an institution that lacks your counterpart’s capability or credibility is a waste of time. Verify credentials and capabilities before signing.
❌ Myth
“SMEs will naturally become bankable if they have access to guarantees.”
✅ Reality
Bankability requires capacity building, financial literacy, and business development support. The IFC–Tamwilcom partnership includes advisory services and capacity building precisely because guarantees alone are insufficient. SMEs need to be developed, trained, and supported to become bankable borrowers.
❌ Myth
“Risk-sharing partnerships in Morocco will follow the same model as other countries.”
✅ Reality
The IFC–Tamwilcom model is replicable but requires adaptation to Morocco’s specific context. Morocco has a unique combination of agricultural economy, supply chain development priorities, and local guarantee infrastructure. Different countries have different SME sectors, financing gaps, and institutional frameworks. A successful risk-sharing model must be customised for each country’s specific conditions.
Section 10 — GTsetu
10
How GTsetu Helps You Find the Right Finance Partner in MENA and Beyond
IFC and Tamwilcom are established international and national institutions. Most businesses are not that fortunate — and even when a government program exists, identifying whether it can connect you to the right financing opportunity requires systematic evaluation. GTsetu is the verified B2B finance discovery platform that enables this evaluation at scale, across 100+ countries, before you reveal a single confidential detail.
🌐 Platform Spotlight — GTsetu
Find Verified Finance Partners, Guarantee Funds, and SME Networks Across 100+ Countries — Anonymously, Securely, With Zero Broker Fees
Every company on GTsetu is verified using government tie-ups on 6 key points: Name, Address, Registration Number, Company Status, Company Type, and Date of Certificate of Incorporation. This is the foundation of trust. Additional information such as regulatory approvals, guarantee capacity, and track record is self-reported by companies. You evaluate who is real before you engage. You share nothing sensitive until an NDA is countersigned. And you pay no broker commission on any collaboration formed — the deal is entirely between you and your partner.
✅
6-Point Government-Sourced VerificationName, Address, Registration Number, Company Status, Company Type, Date of Incorporation confirmed using government tie-ups.
🕵️
Anonymous DiscoveryEvaluate verified partner profiles without revealing your identity until mutual interest is confirmed.
📄
Built-In NDA WorkflowShare financial data only after NDA is executed — full audit trail, no external legal required.
🚫
Zero CommissionNo broker fees — your risk-sharing agreement, guarantee facility, or co-lending deal is entirely between you and your partner.
🌍
100+ CountriesMENA, Africa, Asia, Europe — find finance partners in every market.
🔐
Encrypted CollaborationShare financial specifications, guarantee terms, and partnership agreements securely between verified partners.
What IFC × Tamwilcom Achieved — What GTsetu Enables For You
What IFC × Tamwilcom Achieved
What GTsetu Enables for You
Why This Matters
Partnered with established, credible international and local institutions with proven track records
✓ Browse verified company profiles with government-sourced verification before engaging
You evaluate the partner’s verified legal identity, not marketing claims
Targeted specific sectors (agriculture and supply chains) with clear financing gaps
✓ Filter by self-reported sector focus, guarantee capacity, and track record (validate independently)
Find partners with the specific sector focus and financing capacity your SME segment requires
Structured a risk-sharing facility with clear terms and implementation mechanisms
✓ Built-in NDA and document workflow protects your partnership terms from the first conversation
Your partnership structure and commercial terms are protected at every stage
Combined IFC’s global risk capital with Tamwilcom’s local guarantee infrastructure and bank network
✓ Self-reported partner profiles show geographic coverage, guarantee capacity, and bank relationships
Identify complementary capabilities — the gap between your capital and their market reach
Zero intermediary in the IFC-Tamwilcom relationship — direct strategic alliance
✓ Zero commission on any partnership — all terms are direct between the two parties
No broker splits your margin or misaligns your commercial terms
FAQ
?
Frequently Asked Questions
Q
What exactly is the IFC–Tamwilcom partnership?
The International Finance Corporation (IFC) and Tamwilcom, Morocco’s Central Guarantee Fund, created a risk-sharing facility to support Moroccan SMEs, including agricultural businesses and companies operating in supply chains. The facility is a strategic alliance designed to unlock new financing capacity by reducing the risk exposure of banks lending to SMEs. Under the arrangement, IFC and Tamwilcom share the credit risk of SME loans, enabling banks to lend to segments they might otherwise consider too risky.
Q
Why is this partnership important for Moroccan SMEs?
The partnership addresses a systemic gap in SME financing: Moroccan SMEs in agriculture and supply chains have viable business models but lack access to financing due to bank risk aversion. By sharing credit risk, IFC and Tamwilcom reduce the bank’s exposure, making lending to these segments viable. The initiative is particularly focused on agriculture and supply chain companies, which are critical to Morocco’s economy but often face financing constraints. This is a replicable model for SME finance facilitation across MENA.
Q
What is a risk-sharing facility, and when should I use it?
A risk-sharing facility is a financial arrangement where a guarantor (like IFC or Tamwilcom) shares the credit risk of loans made by banks to SMEs. This reduces the bank’s risk exposure, encouraging them to lend to segments they might otherwise consider too risky, such as agricultural SMEs and supply chain companies. Use this model when banks are risk-averse and SMEs need financing, or when you want to unlock lending capacity in specific sectors. It’s a strategic alliance that combines global risk capital with local guarantee infrastructure.
Q
How can I find a finance partner for SME financing?
The systematic approach involves four steps: (1) Define your financing gap precisely — what specific SME segments, sectors, or geographies need financing? (2) Search verified platforms — GTsetu lists verified finance institutions, guarantee funds, and SME networks across MENA and 100+ countries. GTsetu verifies companies using government tie-ups on 6 points: Name, Address, Registration Number, Company Status, Company Type, and Date of Certificate of Incorporation. Additional information like regulatory approvals and track record is self-reported and should be validated independently. (3) Evaluate anonymously first — review verified profiles and self-reported capability data before revealing your identity or financing requirements. (4) Structure the partnership formally — risk-sharing agreement, guarantee facility agreement, or co-lending agreement.
Q
How do I ensure my risk-sharing partnership actually creates lending?
A risk-sharing agreement is the framework, not the lending flow. Execution is the priority. Ensure your partnership includes: (1) a clear implementation plan with specific timelines, (2) bank onboarding and training, (3) SME outreach and capacity building, (4) clear eligibility criteria and guarantee coverage, (5) clear success metrics (volume of loans guaranteed, number of SMEs reached, default rate). The IFC–Tamwilcom initiative’s focus on agriculture and supply chains demonstrates that targeting and measurement are essential.
Q
Does GTsetu charge commission on finance partnerships formed through the platform?
No. GTsetu charges zero commission on any partnership — whether a risk-sharing agreement, guarantee facility, co-lending deal, or supply chain finance arrangement — formed through the platform. The commercial terms of your agreement are entirely between you and your partner. This is a foundational design principle: broker intermediation in finance partnerships typically costs 5–15% of deal value and creates incentive misalignment between the broker and both parties. GTsetu removes the broker entirely. Learn more about GTsetu →
Ready to Find Your Finance Partner in MENA and Beyond? Start on GTsetu.
500+ verified finance institutions, guarantee funds, SME networks, and development finance partners across MENA and 100+ countries. Zero broker fees. Anonymous discovery. Built-in NDA workflows. Your next risk-sharing partnership starts with a verified profile — not a cold introduction.
Business Development Expert | Global Trade & Cross-Border Partnerships
Lui Wang is a Business Development Expert at GTsetu, specializing in international trade, cross-border partnerships, and market expansion strategies. With extensive experience working across diverse business ecosystems, Lui helps companies identify growth opportunities, establish strategic collaborations, and navigate the complexities of global commerce.
His expertise spans manufacturing, supply chain partnerships, technology collaborations, market entry strategies, and international business development. Through GTsetu, Lui works closely with businesses, trade organizations, and industry stakeholders to facilitate meaningful connections that drive sustainable growth across regions and sectors.
Lui is particularly passionate about helping organizations build long-term international partnerships, unlock new markets, and strengthen their global competitiveness in an increasingly interconnected economy.